How to Predict Construction Cash Flow from Activity Curves, WIEB and Billing Rules
Construction cash flow prediction starts by estimating how each activity is likely to consume cost and produce work over time before the main contract payment terms are applied. An activity may be linear, balanced, front-loaded, back-loaded, milestone-based or hybrid. The predicted work curve then has to be translated into a billable curve because Work Inspection Requests (WIRs), measurement rules, Work in Excess of Billings (WIEB), materials-on-site provisions and billing cut-offs can prevent completed or procured work from entering the payment application in the same period.
This distinction matters because engineers often know the programme, quantities and site sequence well but do not necessarily have a detailed financial model. A useful forecast does not start by guessing one project-wide S-curve. It starts by asking what each major activity actually does over time, what part of that work can be valued, and what causes the activity's cost, work, billing and cash to occur at different times.
A practical way to think about it: predicted activity curve → billable curve → cash curve. The first is mainly an execution forecast. The second is heavily influenced by measurement and contract rules. The third adds payment timing and other commercial terms.
1. What Are We Actually Predicting?
When the period-by-period cost of an activity is already known, no prediction is necessary. For example, if a supplier agreement says that the contractor will pay fixed amounts at specific milestones, those scheduled payments can simply be entered as scheduled cash flows.
Prediction is needed when the user knows the activity's total cost, start, finish and general execution method, but does not yet know how that value will be distributed across the intervening periods.
At that point there are three different curves to keep separate:
- Activity cost or work curve: how the activity is expected to progress and consume resources.
- Billable curve: how much of that work or material can enter the contractor's valuation or payment application.
- Cash curve: when the certified or otherwise payable amount is actually received or paid.
The first curve is the main subject of this article. The second is where WIEB, WIRs and materials on site become important. The third belongs to the broader project cash-flow model.
2. Start With the Activity Before Looking at the Contract
Before applying payment terms, estimate the natural shape of the activity. The key question is not simply, “How long does it last?” It is, “What causes cost and production to build up during that duration?”
Useful non-contract variables include:
- mobilization effort before production starts;
- procurement and fabrication lead time;
- how quickly labour and plant reach full production;
- whether the work is repetitive or one-off;
- the mix of labour, material, plant and subcontract cost;
- whether expensive materials are purchased early;
- whether significant testing, commissioning or closeout remains at the end;
- whether site access or predecessor activities constrain early production;
- whether the activity can progress continuously or only in discrete areas or batches.
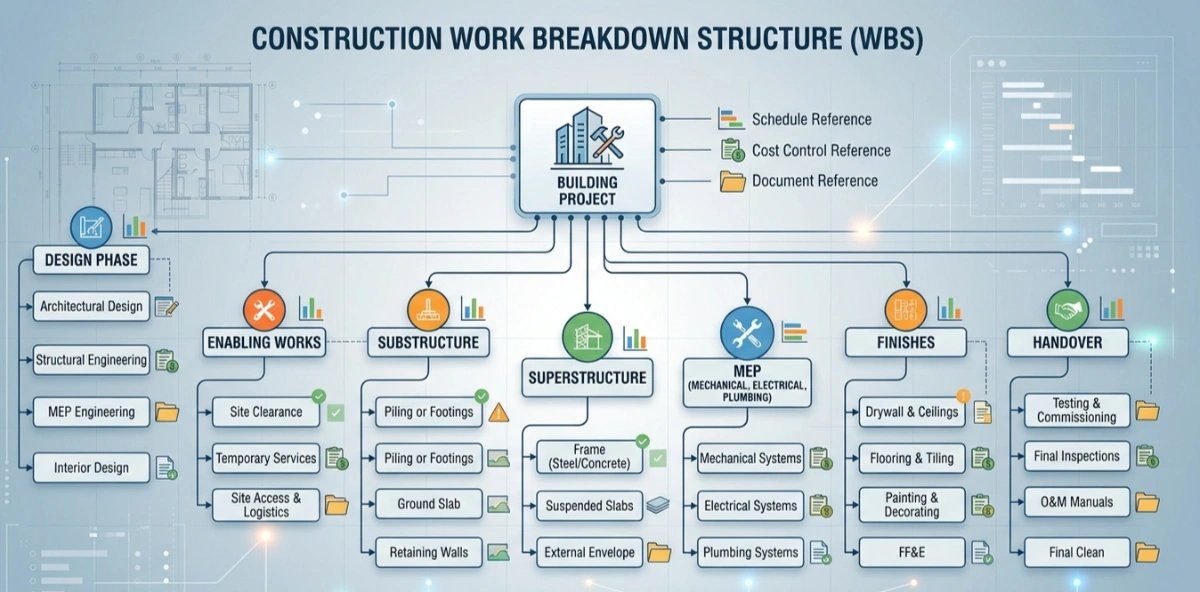
If the project scope is not yet organized into forecastable activities, a Work Breakdown Structure (WBS) can help divide the work into meaningful packages before cost curves are assigned.
3. Common Activity-Curve Shapes
Linear distribution
Linear distribution assumes the same value in every period. If an activity costs $600,000 and lasts six months, the forecast is $100,000 per month.
This is useful as a neutral starting point, but it is often too simple for procurement-heavy, mobilization-heavy or commissioning-heavy activities.
Balanced S-curve
A balanced S-curve represents a slow start, faster production through the middle, then a gradual finish. A convenient normalized cumulative profile is:
\[P(t)=3t^2-2t^3\]
where \(t\) runs from 0 at the start of the activity to 1 at completion. The cumulative activity value at time \(t\) is then:
\[C(t)=V\times P(t)\]
where \(V\) is the total activity cost or value. The cost allocated to one period is the difference between two cumulative points:
\[\text{Period Cost}_n=C(t_n)-C(t_{n-1})\]
The important idea is not the particular equation. It is the separation between a cumulative progression curve and the period-by-period amounts derived from it.
Front-loaded activity
A front-loaded activity consumes more cost early. Mobilization, temporary facilities, enabling works, some earthworks, early equipment procurement and certain specialist packages can behave this way.
Back-loaded activity
A back-loaded activity consumes or produces much more value later. This is common when early periods are dominated by design coordination, approvals, procurement or access constraints and the high-value installation happens later.
Milestone or hybrid activity
Not every activity should be forced into a smooth curve. Long-lead equipment and specialist packages may combine a low continuous curve with discrete events such as advance, manufacturing, delivery, installation and testing. When the amounts and dates are known, scheduled values are better than inventing a smooth mathematical curve.
4. How to Predict Whether an Activity Is Front-, Balanced- or Back-Loaded
The best forecast normally comes from the activity's execution logic. The following examples illustrate the reasoning rather than prescribe universal curves.
| Activity | Likely profile | Reason |
|---|---|---|
| Earthworks | Linear to mildly front-loaded | Plant mobilizes early and measurable production can start quickly. |
| Structural concrete | Balanced/repetitive | Once the cycle is established, formwork, reinforcement and pours repeat at a relatively stable rate. |
| MEP subcontract | Often back-loaded | Early months may contain submittals, procurement, coordination and embedments; high-value installation accelerates later. |
| Facade | Moderately back-loaded | Shop drawings, samples, testing, procurement and fabrication precede full installation. |
| Soft landscaping | Short and concentrated | Material delivery and installation can occur almost together over a short period. |
| Long-lead equipment | Milestone/hybrid | Manufacture, shipment, delivery, installation and testing may create discrete value steps rather than a smooth curve. |
Example: why an MEP subcontract can be strongly back-loaded
Consider an MEP subcontractor on a building project. After mobilization, a substantial amount of engineering effort may be spent on material submittals, shop drawings, coordination, procurement and embedded items during the structural phase. One third of the project duration may pass while the subcontractor has produced relatively little measurable installation value on site.
Once areas are released, installation can accelerate rapidly. Ductwork, pipework, cable containment, equipment, second fix, testing and commissioning may then generate much larger monthly valuations. A simple linear curve would overstate early production and understate later production.
An advance payment can improve the subcontractor's early cash position, but that is a contract-payment mechanism. It does not mean the underlying installation curve itself should be made front-loaded. For advance-payment mechanics, see Advance Payment in Construction Contracts.
5. From Activity Curves to the Project Outflow Curve
Once each activity has a period-by-period distribution, the project outflow forecast is built by summing the activities vertically for each period.
| Activity | M1 | M2 | M3 | M4 | M5 |
|---|---|---|---|---|---|
| Foundations | 30 | 80 | 90 | 0 | 0 |
| Structure | 0 | 40 | 120 | 180 | 160 |
| MEP | 0 | 0 | 20 | 60 | 100 |
| Total | 30 | 120 | 230 | 240 | 260 |
The quality of the project curve therefore depends on the quality of the activity assumptions. A model with 30 well-chosen activities can be more useful for a commercial decision than a much larger schedule with weak cost distributions.
6. Why Work Performed Is Not Necessarily Billable Work
Physical progress, incurred cost and billable value are not the same thing. An activity can consume substantial labour and material while still producing little or no amount that can be included in the current payment application.
This difference is commonly described in forecasting as Work in Excess of Billings (WIEB): work or cost that has progressed but is not billed in the same period.
WIEB should not automatically be entered as one percentage for every activity. It is better estimated from the activity's execution pattern and the rules that determine when its value becomes measurable, inspectable and billable.
7. How to Estimate WIEB by Activity
Activity-specific WIEB is influenced by several practical factors:
- Measurement rule: can partial work be valued, or must a complete element or defined quantity be achieved?
- Inspection requirement: must a WIR, test or other acceptance record be completed before the work can be included?
- Activity duration: long activities are more exposed to monthly cut-off effects than very short activities.
- Billing cut-off: how much completed work typically falls between site progress and the valuation date?
- Documentation lag: quantities, approved drawings, delivery records, test reports or other supporting documents may delay billing even after work is complete.
- Material billing rules: can material on site or off site be valued before installation?
Example: structural concrete near the billing cut-off
Assume a slab is almost ready to pour at the monthly cut-off. Formwork may be nearly complete, reinforcement may be largely installed and embedded MEP items may be in place. The contractor has already incurred substantial cost.
However, if the contract's valuation process requires the completed work to reach a defined inspection or measurement stage, the slab may contribute little or even zero billable value for that period. The unfinished portion becomes WIEB and is carried into the next valuation.
This is why inspection workflow matters financially. For background on the inspection process itself, see Work Inspection Requests (WIR) in Construction.
Example: soft landscaping can have very low WIEB
Soft landscaping behaves differently. The activity may last only a few months, plants and materials may arrive shortly before installation, and much of the delivered material can be installed and measured almost immediately. There may therefore be very little time between cost being incurred, physical work being completed and the work becoming billable.
The correct WIEB assumption for landscaping can consequently be close to zero while the structural concrete or MEP assumptions on the same project are materially higher.
8. How Materials on Site Can Reduce WIEB
A materials-on-site provision can reduce the gap between project expenditure and billable value by allowing eligible materials to be valued before they are incorporated into the permanent works.
Consider reinforcing steel for a slab. Without a materials-on-site provision, the contractor may purchase and deliver a substantial quantity of steel but be unable to bill that cost until the relevant work is measured or accepted. If the contract allows eligible reinforcing steel stored on site to be included in the valuation, part of that expenditure can enter the current payment application earlier.
The effect is usually partial rather than complete because the contract may recognize only an eligible percentage or defined value of the supplier invoice and may require supporting documents, approved materials, secure storage, title transfer or other conditions.
Illustrative example: if $100,000 of reinforcing steel has been paid for and the contract recognizes only 70% of the eligible material value on site, $70,000 may become billable earlier while the remaining material value, labour, formwork and unfinished work can still contribute to WIEB. The actual percentage and conditions are entirely contract-specific.
This means a material-on-site clause can materially improve cash flow on some activities while making very little difference on others. The correct question is not whether the clause sounds favourable; it is how much it changes the actual project funding requirement.
9. Contract Terms Modify the Predicted Curve
Once the natural activity curve is predicted, contract terms determine how that work is translated into billing and cash. Important modifiers can include:
- partial measurement versus completed-element rules;
- WIR, MIR, testing or approval requirements;
- materials on site and, where allowed, off-site material valuation;
- milestone payments for manufactured equipment;
- advance payment and recovery;
- retention and its release;
- billing cut-off dates;
- payment-certification and payment periods.
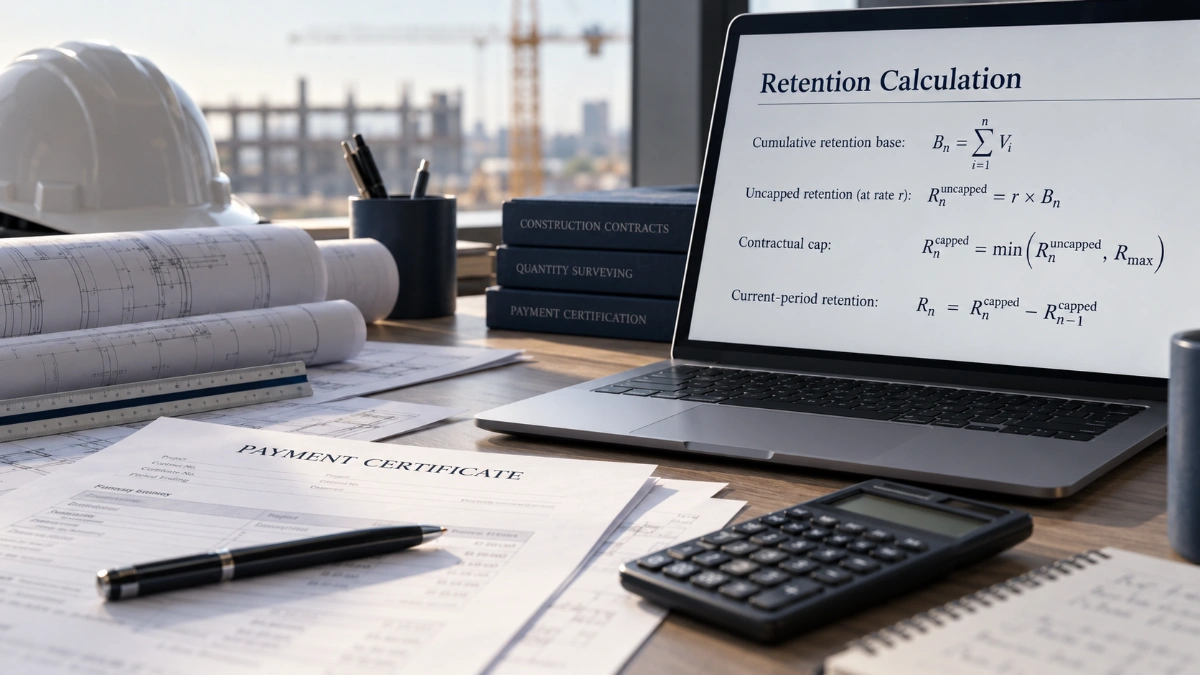
Retention is another timing mechanism that can separate earned value from cash. See Retention in Construction: Formulas, Bonds & Accounting Guide for the detailed treatment.
The distinction is important: the activity curve should describe the execution assumption; the contract terms should then modify how that execution becomes billable and payable. Mixing both into one unexplained S-curve makes the model difficult to understand and difficult to negotiate.
10. Use Sensitivity Analysis to Find the Contract Terms Worth Negotiating
Contractors do not need to fight equally hard over every commercial clause. Some terms have a large effect on project funding; others sound important but barely move the peak negative cash position.
A useful tender or pre-contract test is to run the same activity forecast under several assumptions. For example:
- WIEB at 5%, 15% and 25% for the major work packages;
- no materials-on-site recognition versus partial recognition;
- different client payment periods;
- different retention percentages;
- different advance-payment structures.
If a realistic change in WIEB or materials-on-site treatment moves the peak funding requirement by a large amount, the term deserves serious negotiation. If the effect is negligible, the contractor may have more important issues to prioritize.
This is one area where a dedicated financial model is useful: it converts a contract discussion into a quantified funding impact rather than an argument based only on intuition.
11. Tools for Building the Forecast
The method is independent of software. The right tool depends on how much schedule detail already exists and what decision needs to be made.
| Tool | Useful when | Trade-off |
|---|---|---|
| Primavera P6 | A detailed, current, cost- or resource-loaded programme already exists. | Can provide granular schedule-based forecasting, but requires a properly developed and maintained programme. |
| Microsoft Project | The team needs schedule logic with time-phased task and resource costs at moderate complexity. | Still requires the schedule, resources and cost assumptions to be maintained correctly. |
| Excel | Custom curves, calculations and one-off analysis are needed. | Very flexible, but formulas and scenarios become harder to maintain as the model grows. |
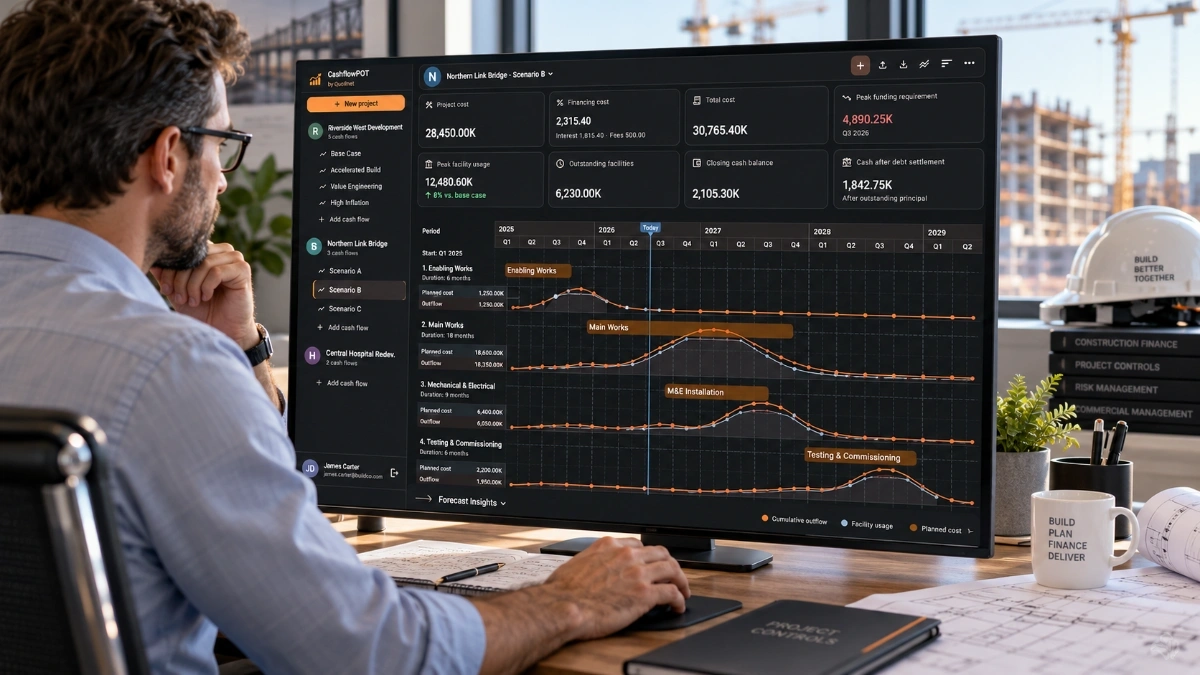
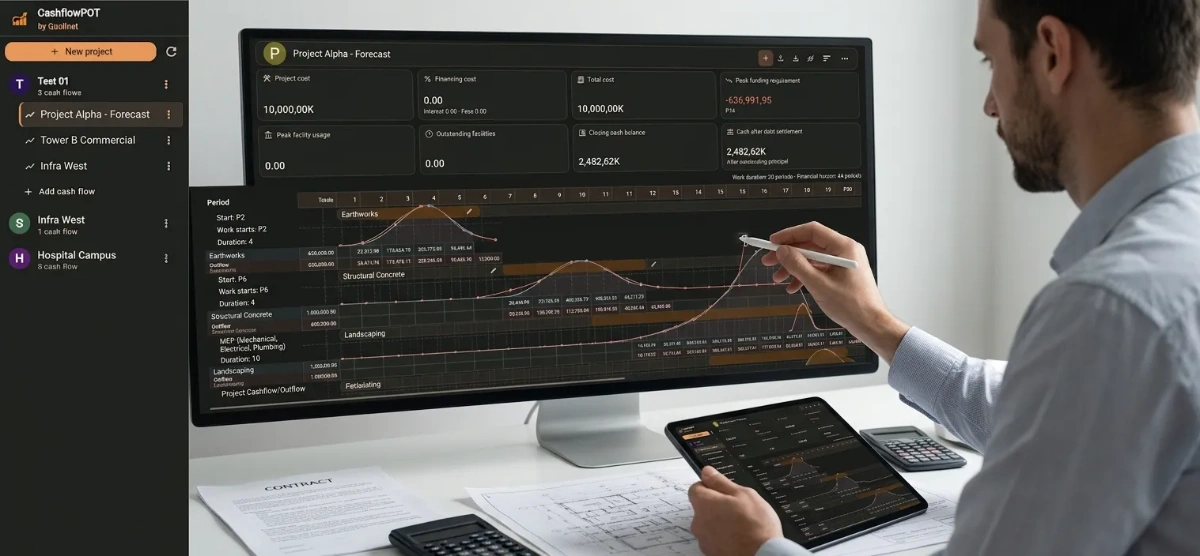
| CashflowPot | The purpose is fast construction financial modelling rather than detailed CPM scheduling. | Uses activity timing, cost curves and commercial assumptions to test project cash flow; it does not replace a detailed planning programme. |
Oracle's current P6 documentation supports planned, actual and remaining cost at resource-assignment level, while Microsoft Project provides time-phased task, resource and assignment cost fields. These tools can therefore support detailed schedule-based forecasting when the underlying programme is maintained properly.
CashflowPot is useful when an engineer or commercial team needs to move quickly from a master activity plan to a financial forecast and test assumptions such as curve shape, WIEB, payment terms and funding sensitivity without building a full detailed programme first. The dedicated product workflow is covered separately in Master Construction Project Cashflow with CashflowPot.
12. Download the Existing Excel Cash-Flow Example
The existing Quollnet Excel example can be used to inspect a time-phased construction cash-flow output. Treat the activity distributions as examples rather than universal deaults; the purpose of this article is to explain how those distributions should be selected.
Download the construction project cash-flow Excel example

Describe your construction project, payment terms and financing assumptions in natural language. CashflowPot can model the forecast, compare funding scenarios and export the results to Excel.
13. From Activity Prediction to the Full Project Cash Flow
The activity forecast is only the first layer. After the outflow curve and activity-specific billing assumptions are established, the project model must still build client inflow separately, apply advance recovery, retention, WIEB, certification and payment timing, and then calculate the cumulative cash position and peak funding requirement.
That complete workflow is explained in How to Create a Construction Project Cash Flow: A Practical Guide for Contractors.
The key principle is simple: do not choose a curve because it looks like a typical construction S-curve. Choose it because it reflects how that specific activity mobilizes, procures, installs, gets inspected, becomes billable and ultimately turns into cash.
References
Oracle Primavera P6 Professional User Guide — Enter cost information for resource assignments