Construction Retention: Caps, Guarantees and Cash Flow
Construction retention is money withheld from construction payments at a specified rate up to an agreed cap. Variations may or may not alter that cap. Cash-flow forecasting must account for retention release dates, alternative guarantees, bank fees and possible extensions.
Retention calculations
A deduction rate of 10% and a maximum retention cap of 5% are not contradictory. For each interim certificate, deduct the lesser of the eligible new valuation multiplied by the rate or the remaining cap after previous deductions. A $1 million contract with a $50,000 cap stops accumulating retention when the total withheld reaches $50,000.
Worked example: cumulative cap
| Certificate | New eligible work | Retention deducted | Retention held |
|---|---|---|---|
| 1 | $200,000 | $20,000 | $20,000 |
| 2 | $200,000 | $20,000 | $40,000 |
| 3 | $200,000 | $10,000 | $50,000 |
| 4 | $200,000 | $0 | $50,000 |
These values assume that the eligible certified work is positive and that no retention has yet been released. Later certificates, negative adjustments and different valuation bases require contract-specific calculations.
How to Calculate Retention in a Progress Payment Certificate (PPC)
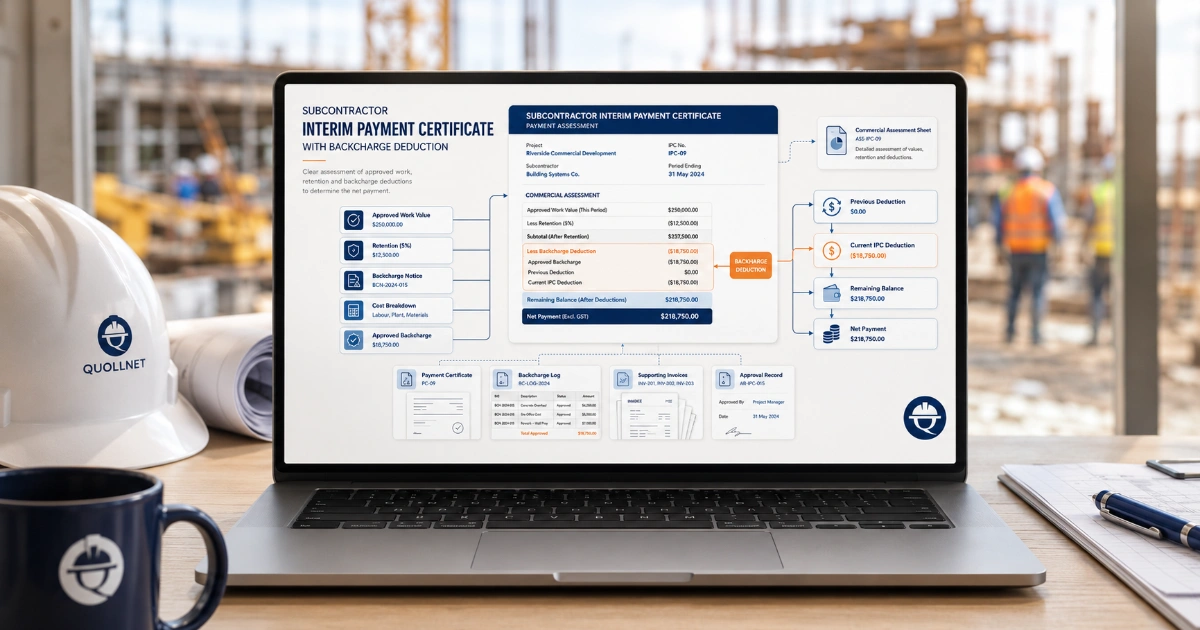
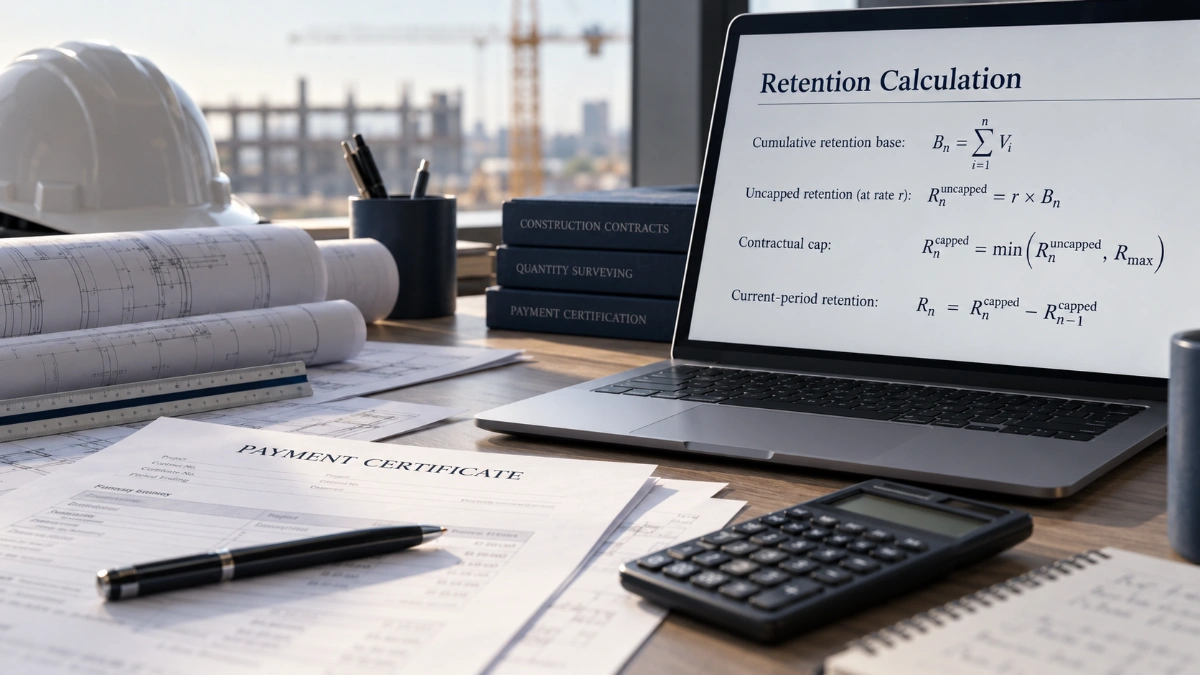
A Progress Payment Application or Certificate should distinguish original contract information from the cumulative certified value of executed work. For the retention line, use the contractually eligible cumulative valuation, apply the retention deduction rate subject to the cap, and subtract retention previously deducted (adjusted for any releases or credits). Do not confuse the original contract amount that determines the cap with the work and adjustments that determine the deduction base.
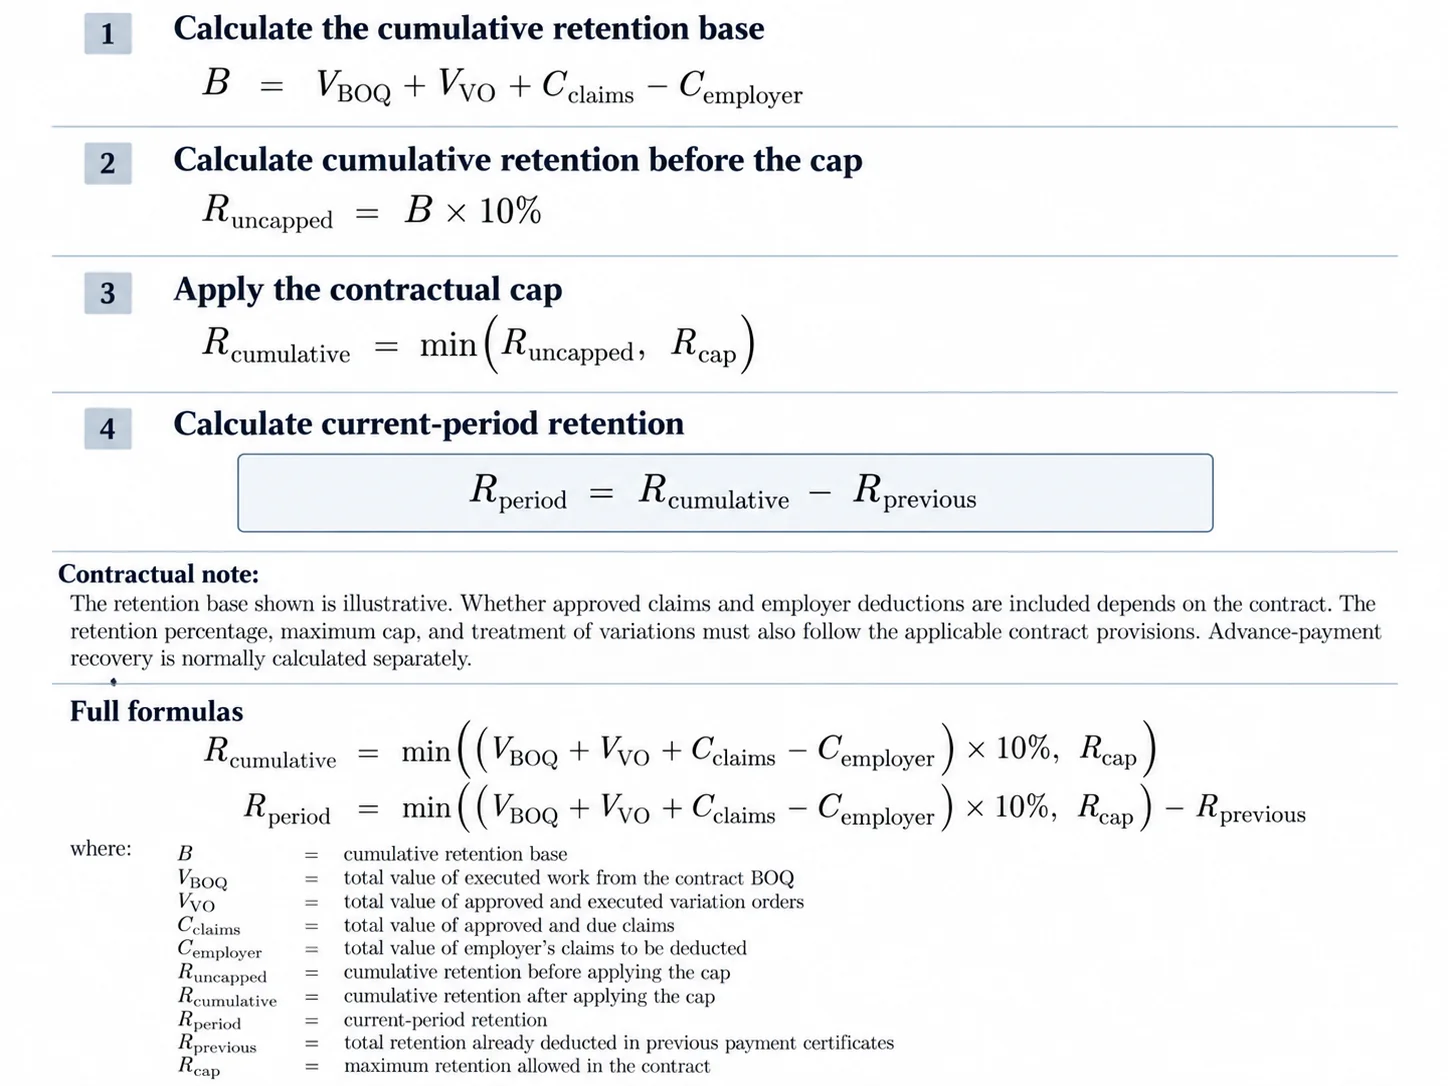
Illustrative cumulative PPC retention formula
\[R_{\mathrm{current}}=\min\left[R_{\mathrm{cap}},\;r\left(V_{\mathrm{BOQ}}+V_{\mathrm{VO}}+C_{\mathrm{claims}}-C_{\mathrm{employer}}\right)\right]-R_{\mathrm{previous}}\]Where the amounts are cumulative up to the current PPC: \(V_{\mathrm{BOQ}}\) is executed and eligible BOQ work; \(V_{\mathrm{VO}}\) is eligible approved and executed variations; \(C_{\mathrm{claims}}\) is approved and due contractor claims only if the retention clause makes them subject to retention; \(C_{\mathrm{employer}}\) is the part of employer claims or deductions that the contract expressly removes from the retention base; \(r\) is the retention deduction rate (10% in this example); \(R_{\mathrm{cap}}\) is the contractual maximum retained amount; and \(R_{\mathrm{previous}}\) is the cumulative retention already deducted in previous PPCs, appropriately adjusted for prior releases and corrections.
Contract caution: Employers' claims and set-offs should not automatically reduce the retention calculation base. They are generally shown as separate deductions from the payment calculation unless the contract provides otherwise. Do not deduct employer claims once in the retention base and again in the PPC without understanding that they affect different calculations. Likewise, approved claims may not all be retention-eligible. Check the contract before applying the illustrated formula.
If cumulative retention already held has reached the cap, normally no additional retention deduction is made unless a contractual adjustment permits it. Credit notes, negative valuations, retention releases and a revised retention cap need specific reconciliation; the simplified formula assumes an ordinary positive payment cycle without such adjustments.
Worked PPC No. 3 example
| Item (USD) | Cumulative | Previous PPCs | Current period |
|---|---|---|---|
| Executed BOQ works | 420,000 | 230,000 | 190,000 |
| Approved executed VOs | 30,000 | 20,000 | 10,000 |
| Approved due claims (excluded from retention in this example) | 10,000 | 0 | 10,000 |
| Gross work valuation | 460,000 | 250,000 | 210,000 |
| Advance recovery | 40,000 | 20,000 | 20,000 |
| Retention (10% of eligible BOQ + VO work) | 45,000 | 25,000 | 20,000 |
| Net certified payment | 375,000 | 205,000 | 170,000 |
Under these assumptions, the cumulative retention base is $450,000: executed work of $420,000 plus eligible variations of $30,000. The 10% cumulative retention is $45,000, below a $50,000 cap, and retention in PPC No. 3 is $45,000 less the $25,000 already deducted: $20,000. The previous $25,000 should be supported by the accompanying retention calculation schedule, in which each earlier PPC occupies one row.
In the main PPC, distinguish cumulative valuation, cumulative advance recovery, cumulative retention, employer deductions, earlier certified net amounts and the current certificate. Track the amount actually paid to the contractor separately for the accounts department; earlier unpaid certificates must not be certified again merely because the cash has not arrived.
What belongs on the retention schedule attachment?
Record the PPC number and period, cumulative eligible BOQ value, executed variations, retention-eligible claims, employer deductions included in the base where contractually permitted, contractual retention rate and cap basis, previous retention withheld, current deduction, any retention releases and the cumulative amount still held. The schedule supports the retention line in the PPC and makes its basis auditable by the engineer, quantity surveyor and employer.
Variations
A fixed cap of $50,000 remains unchanged if the contract price increases or decreases, unless the contract expressly adjusts the basis. After a reduction to $700,000, $50,000 is equivalent to 7.14% of the revised value. A cap calculated from the revised price might instead become $35,000. Check contract wording.
Fixed cap versus revised-value cap
| Revised contract price | Original fixed cap | Effective cap |
|---|---|---|
| $1,000,000 | $50,000 | 5.00% |
| $1,400,000 | $50,000 | 3.57% |
| $700,000 | $50,000 | 7.14% |
If the same 5% cap is contractually linked to the revised contract price, the cap becomes $70,000 or $35,000 in the latter two cases. Any adjustment to retention previously withheld must follow the contractual mechanism and certification procedure.
When retention is due versus when it is paid
Some contracts release retention in two stages around taking-over and the end of a defects period, but the proportion, date and certification requirements are contract-specific. A common 50/50 example is not a universal rule. A payment becoming due is different from certification and from receipt of money in the contractor's bank account. Cash-flow forecasts should record anticipated receipt dates, and scenario analysis should allow delays.
Retention guarantees
Where accepted, a bank retention guarantee can replace withheld cash. The employer releases the retention and holds guarantee security. The contractor pays bank fees and may provide collateral. An uncalled guarantee does not normally require repayment of the guarantee principal. If the bank pays a valid claim, reimbursement may become due.
Forecasting cash flow
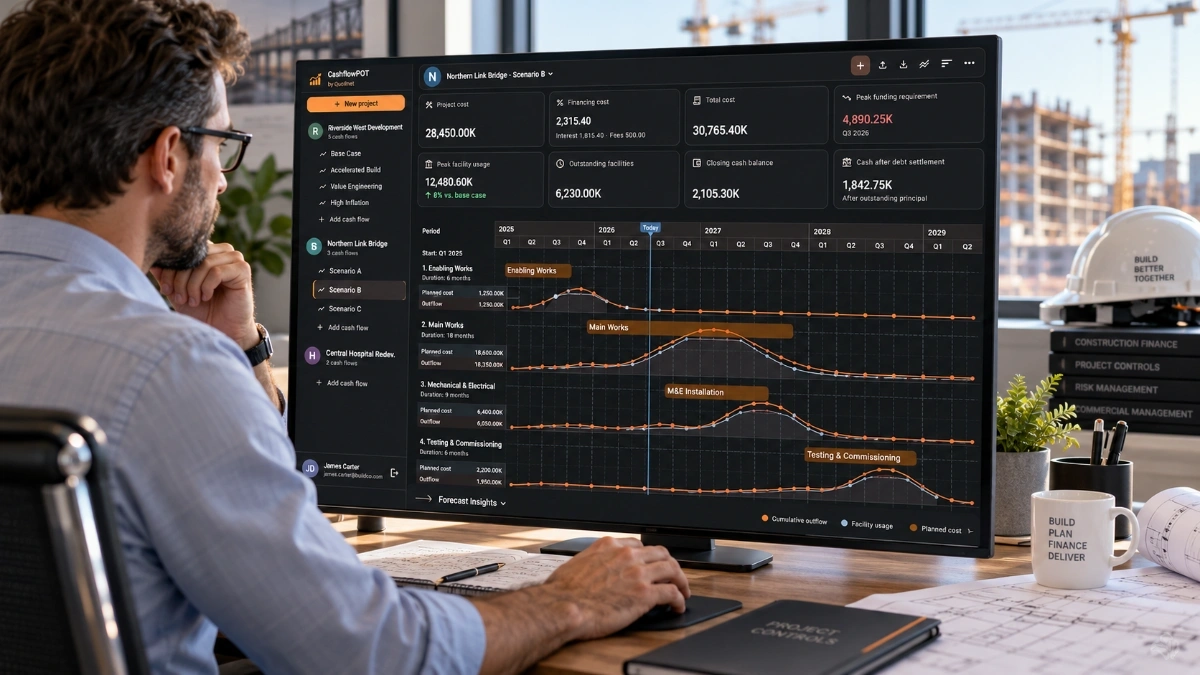
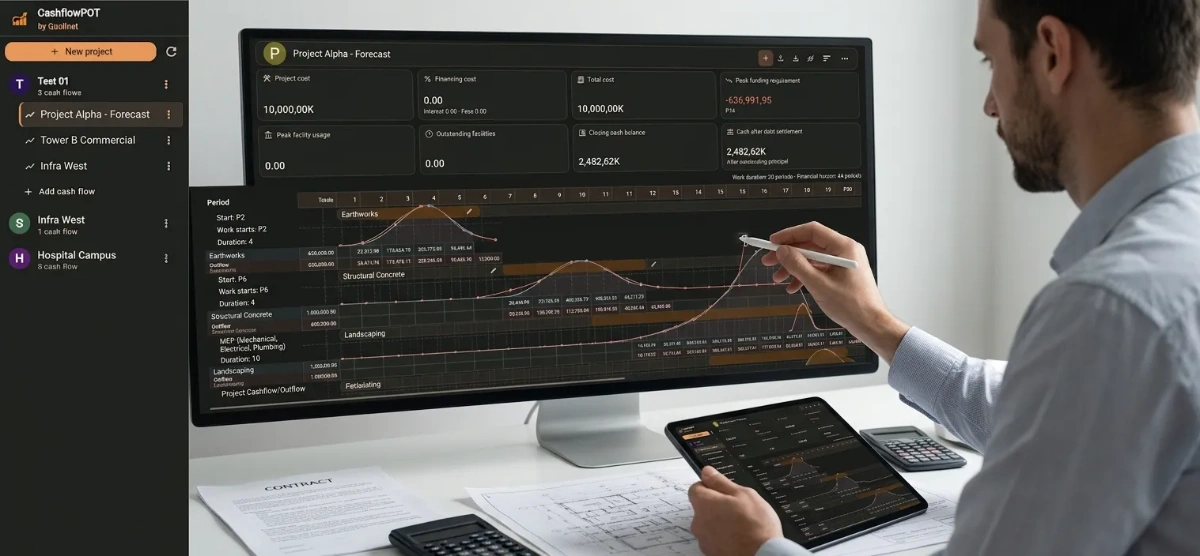
A synthetic financing facility may model early retention release: an immediate facility inflow, then a future repayment offset against the retained employer inflow at the expected release date. This is a modelling technique, not a real loan. Add guarantee fees, collateral and possible partial or full calls separately. If discharge is delayed, add renewal fees and update payment timing only if the actual expected cash receipt changes.
Illustrative $50,000 bank guarantee
Suppose $50,000 of retention would otherwise be paid after twelve months. The employer accepts a guarantee and pays the withheld money now. At an illustrative 2% annual guarantee commission, one year's fee is $1,000 before other charges. If the bank demands new $10,000 cash margin, immediate freely available cash is $39,000 after margin and commission. The margin is a separate restricted cash item, not a financing fee.
| Cash-flow entry | Early release | Scheduled final release |
|---|---|---|
| Original employer retention inflow | $0 | +$50,000 |
| Synthetic financing inflow | +$50,000 | $0 |
| Synthetic repayment | $0 | −$50,000 |
The two future entries cancel. Do not also move the original employer inflow forward: that would count the early cash twice. The synthetic repayment is not a real bank loan obligation when a guarantee simply expires.
Discharge, partial call and full call
If the bank guarantee expires or is returned without a claim, there is no bank principal repayment outflow. If $20,000 is validly called and paid, forecast the corresponding $20,000 contractor reimbursement when due. If the full $50,000 is paid, forecast the larger reimbursement. The timing of the bank payment may differ from DLP expiry. The guarantee instrument and bank indemnity govern these consequences.
Delayed close-out and renewal fees
A snag list delivered near defects-period expiry can result in genuine outstanding repairs, delayed certification or a dispute about guarantee discharge. A delayed security discharge does not automatically mean the employer's retention cash payment was delayed, particularly if it was already paid in exchange for the guarantee. At the same illustrative 2% annual rate, renewing a $50,000 guarantee for three months adds about $250 in commission before other charges. Include that fee and continuing use of the bank facility; only move cash receipt or synthetic offset dates if actual expected cash timings have changed.
Retention and defects
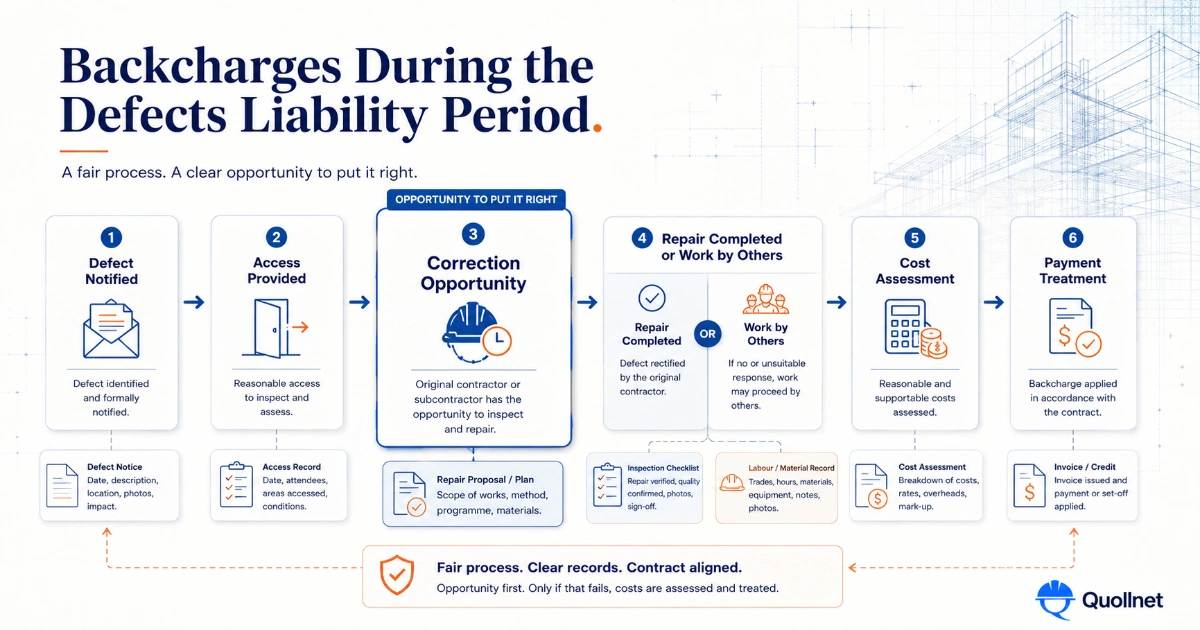
Defect notification, correction and security release are separate contractual mechanisms. For detailed DLP issues, read the defects liability period guide.
Retention accounting and practical checks
Retention is a cash-flow deduction, not necessarily a deduction from revenue. Depending on contractual rights and accounting standards, a contractor's retention balance may be presented as a receivable or contract asset. Its classification depends on whether the right to consideration is unconditional or depends on further performance. Likewise, employer accounting follows the underlying cost, liability and certification arrangements. Avoid assuming a single universal journal entry.
Before relying on the forecast, confirm the deduction rate; eligible valuation base; cap amount and whether variations adjust it; cumulative retention previously deducted; partial-release milestones; actual expected payment dates; eligibility for replacing retention with a guarantee; bank fees, margins and expiry; and remedies for partial or full calls.
Further reading
Construction project cash-flow forecasting covers contract inflows and funding needs. The CashflowPot tutorial explains financing scenarios and cash-flow modelling.
Download the PPC and Retention Payment Application (Excel)
Download the Progress Payment Application and Retention Schedule (Excel). The workbook includes the PPC application, a one-row-per-PPC retention register, and instructions for cumulative, previous and current-period calculations. Review the retention base, cap, claims and payment terms against the governing contract before using it for a live certificate.